Source numbers link to evidence. [Inference] marks analytical judgment, including motion classifications and causal explanations. Public evidence does not establish every internal decision or metric.
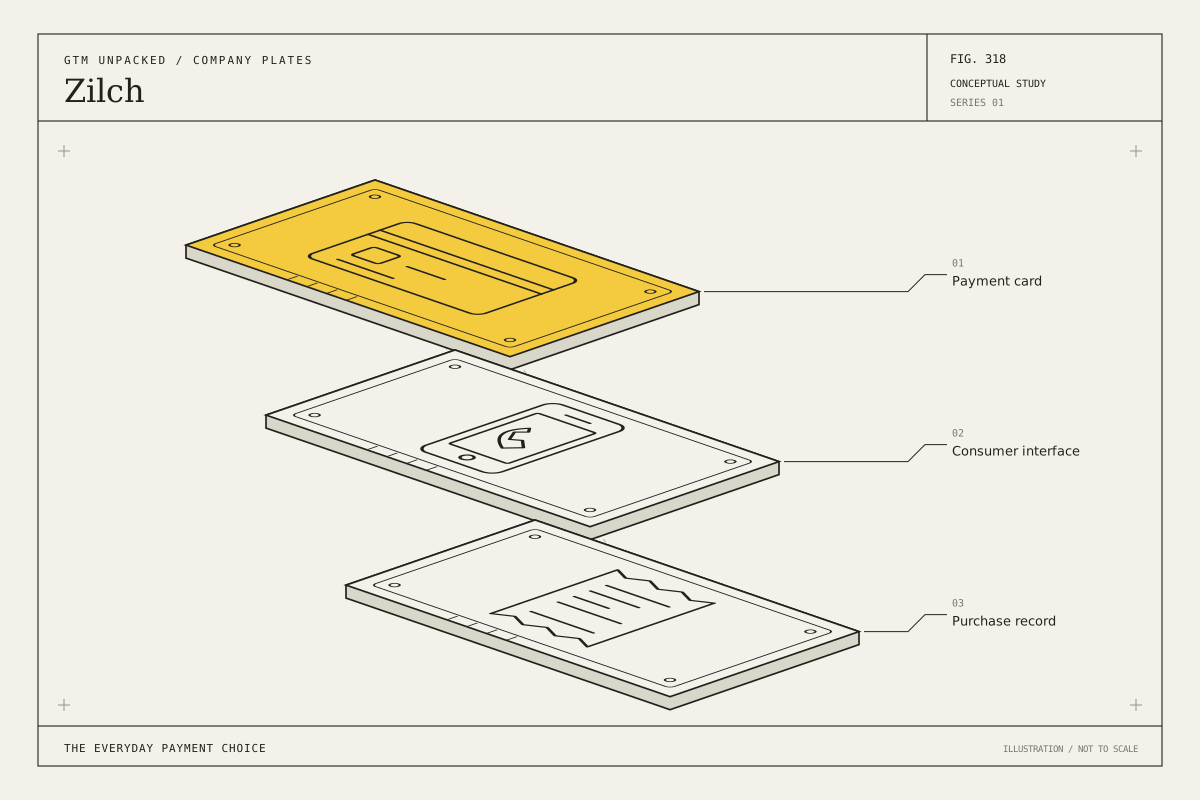
Conceptual illustration arranging a payment card, phone, and receipt as an everyday payment study, distinguishing instrument, interface, and record without claiming credit outcomes.
- Company
- Zilch · Consumer payments · zilch.com
- Conversion motions
- [Inference] This research classifies Zilch as Product Led and Marketing Led.
- Zilch beachhead and target customer
- [Inference] Consumers using an app for payment and credit choices.
- Product and buying complexity
- [Inference] The consumer decision is simple; credit, fraud, funding and support complicate the underlying business.
- Market at entry
- [Unverified] This focused brief does not establish the full market conditions at first sale.
- Evidence
- Evidence brief · 1 linked source · research date · method and limitations
The ten-step Revenue Engine reading map
These links locate relevant evidence. A linked section does not imply every detail of the step is publicly established.
- Acquire Your First Customers: Founder Led Sales Read first customers
- Embrace GTM Experimentation Read experiments & lessons
- Understand Your GTM Motion Options Read GTM motion
- Pick Your GTM Motion Not established in this entry
- Generate a Lead Read GTM motion · Read experiments & lessons
- Turn Leads into Paying Customers Read GTM motion
- Retain and Grow Your Customers Read retain & expand
- Build Your GTM Team Not established in this entry
- Plan Your Tech Stack Read experiments & lessons
- Optimize and Scale Through Metrics Not established in this entry
Zilch: Origin and evidence boundary
The first paid customer and founder closing sequence were not established in this focused evidence brief.
Zilch identifies Philip Belamant as co-founder and CEO, with more than twenty years of fintech experience and IT degrees from RAU University. Its official profile describes a consumer payments app usable where Mastercard is accepted and reports registered customers, payment volume and revenue run rate separately. Those company figures are not audited unit-economics measures. [1]
[1]Zilch: Motion and buyer logic
[Inference] Consumers using an app for payment and credit choices.
[Inference] The consumer decision is simple; credit, fraud, funding and support complicate the underlying business.
[1]Zilch: Retention and expansion hypothesis
[Inference] More frequent retained payment activity can increase account value; credit quality remains essential.
[Unverified] Individual CSM ownership, enablement conversion and renewal cohorts were not established in this brief.
Zilch: Critical reading
[Inference] Registered users and transaction volume are weak substitutes for retained active customers and risk-adjusted contribution. Advertising economics and lending economics should be assessed separately where relevant.
[Unverified] The inspected material does not establish failed-channel experiments or a complete causal account of growth.
Zilch economics at a glance: Pricing is only half the story.
Exact current pricing was not verified in this brief.
[Inference] More frequent retained payment activity can increase account value; credit quality remains essential.
[Inference] Registered users and transaction volume are weak substitutes for retained active customers and risk-adjusted contribution. Advertising economics and lending economics should be assessed separately where relevant.
Not publicly verified in this brief.
Not publicly verified in this brief.
The people in the Zilch GTM story: People & capabilities.
Philip Belamant
People identified in the sourcePhilip Belamant — co-founder and CEO; RAU University IT degrees and longstanding fintech experience.
See the source-backed account above; additional skills and training are not inferred as fact.
[1]Zilch GTM: critical reading and analysis: Why it worked.
Where it breaks.
What worked—and why
[Inference] Registered users and transaction volume are weak substitutes for retained active customers and risk-adjusted contribution. Advertising economics and lending economics should be assessed separately where relevant.
What did not work
No substantiated failed experiment established in the inspected evidence.
What could have been better
[Inference] Validate the proposed growth mechanism with paid conversion, implementation cost and retained customer outcomes.
What another founder can use
[Inference] More frequent retained payment activity can increase account value; credit quality remains essential.
Zilch go-to-market FAQ: The questions that matter.
What does this case establish about Zilch?
The inspected source supports the specific product, people or distribution facts in the origin section; a full chronological reconstruction remains incomplete. [1]
Is the full GTM history of Zilch verified?
No. This is a focused evidence brief. The page distinguishes inspected claims from analytical hypotheses and lists the remaining gaps.
Which go-to-market motions is Zilch classified under?
[Inference] This research classifies Zilch as Product Led and Marketing Led. Motion labels describe routes across segments and periods, not measured revenue shares.
Zilch sources and open questions: Follow the sources.
- Zilch — inspected company evidence Zilch · primary
Origin, product, team or current commercial route described in the source; narrower claims are attributed in the text.
What remains unverified
Evidence brief rather than a full historical GTM reconstruction.
First contracts, complete hiring sequence, pricing history, CAC and retention require further source verification.
No historical website screenshot or named account expansion is represented as verified.
No verified visual capture is attached to this entry. A current screenshot is not a substitute for a historical capture.